In 2007, the trustees of Harbor Towers, the twin 40-story concrete towers between the New England Aquarium and Rowes Wharf, voted to spend $75.6 million replacing the buildings' heating and cooling systems. The bill landed on owners as a special assessment ranging from $70,000 to $400,000 per unit, due that November. Some residents sold rather than pay it. A unit owner who happened to be an engineer challenged the repair plan and sued the trustees. A contested election followed. By the next January, more than 95 percent of the assessment had been collected, and the building moved on.
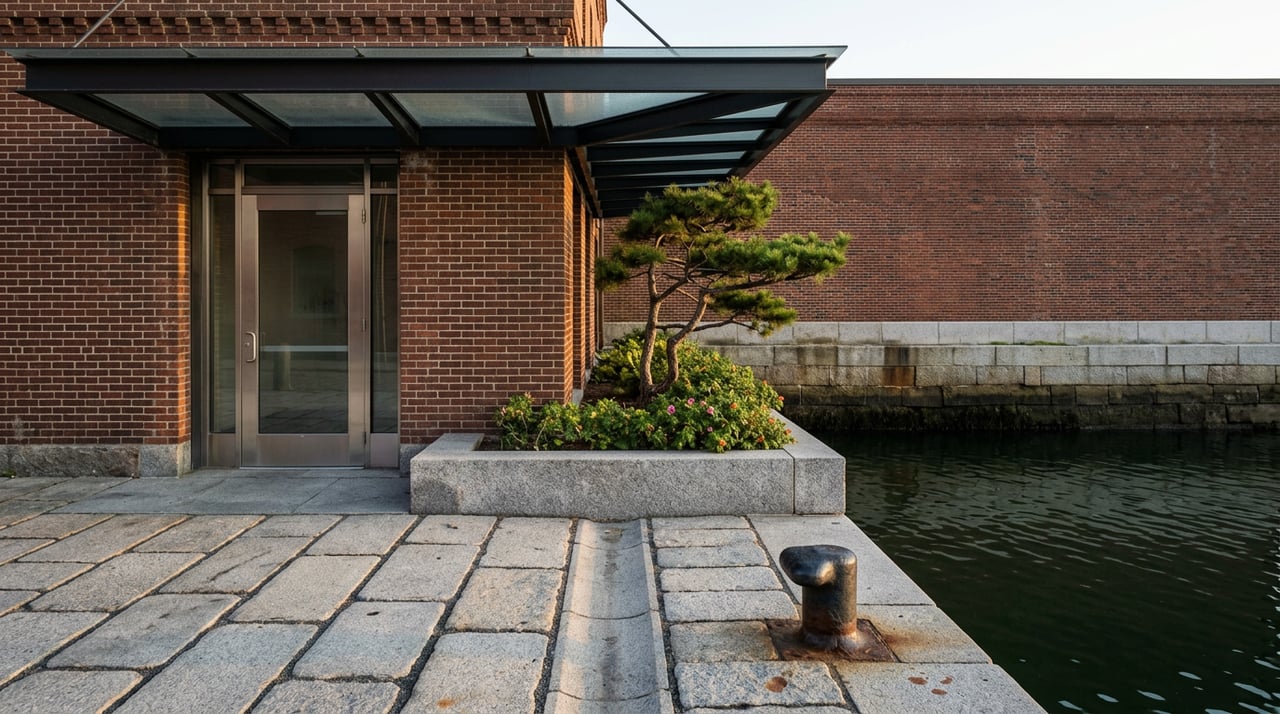
It didn't stay quiet. In April 2025, Harbor Towers started a $20 million project to reinforce its ground-floor coastal defenses against sea level rise, a response to flooding from two nor'easters back in 2018. And on July 20, 2026, the US Army Corps of Engineers released a draft $10 billion plan to protect 16 miles of Boston's coastline from the same kind of water, with specific proposals for a floodgate across Commercial Street in the North End and continued resilience planning at Long Wharf, one of the lowest points on the entire waterfront.
If you've been comparing condo listings between the Waterfront and the Seaport, you've probably noticed the Waterfront trades at a real discount per square foot. Most buyers assume that gap is about age or amenities. The Harbor Towers timeline suggests something more specific: the discount is partly a price on who absorbs the next repair bill, and Boston just put an actual number on how big that bill could get.
The Discount Isn't About Age. It's About Exposure.
The Waterfront here means the older corridor along Atlantic Avenue and the wharves, Rowes Wharf, Battery Wharf, Lewis Wharf, Burroughs Wharf, Commercial Wharf, Harbor Towers, running between the Aquarium and the North End. This is a different submarket than the newer South Boston Waterfront section near the Seaport, which trades closer to Seaport pricing.
As of March 2026, Rowes Wharf units sold in roughly the $1,300 to $1,800 per square foot range depending on floor and layout. Battery Wharf and Lewis Wharf conversions showed broader ranges tied to unit size and renovation level, generally landing below Seaport's newest towers. In the Seaport core over that same window, buildings like 135 Seaport Boulevard and St. Regis Residences were trading at $1,506 to $2,255 per square foot, with the Seaport core median sale price near $2.98 million.
That $150 to $500 per square foot gap between the two waterfronts gets explained away as newness. Glass towers, concierge staff, resort-style amenity decks. All true. But it also tracks almost exactly with something else: which buildings were constructed before modern flood-resilient codes existed, and which trustees have already had to write a very large check to keep their building standing.
Here's how the carrying costs actually compare, building by building, using the most recent listing data available:
| Building | Submarket | Price per square foot | Typical monthly HOA fee |
|---|---|---|---|
| Rowes Wharf | Waterfront | $1,300–$1,800 | — |
| Battery Wharf | Waterfront | — | $1,650–$4,287 |
| Burroughs Wharf | Waterfront | — | $1,076–$1,753 |
| 135 Seaport Boulevard | Seaport | $1,506–$1,939 | — |
| St. Regis Residences | Seaport | $1,551–$2,255 | $1,742–$3,528+ |
| 50 Liberty | Seaport | — | $947–$2,460 |
Notice that Battery Wharf's high end, a service-heavy hotel-integrated building, actually rivals St. Regis on monthly fees despite selling for less per square foot. That's not a coincidence. A higher fee on an older building often means the association is already funding the kind of reserve work that a 2025 or 2026 construction never had to catch up on.
The Bill Just Got a Number
For most of the last decade, the risk sitting under Boston's waterfront was theoretical, something planners studied without a firm price tag attached. That changed this summer. The Army Corps' July 2026 draft feasibility report puts Boston's coastal defense need at roughly $10 billion, covering floodwalls, berms, and a proposed storm surge barrier for Fort Point Channel, with the federal government expected to cover about 65 percent and the rest split between state, local, and private sources. Brian Swett, Boston's chief climate officer, called it what it is: "the largest investment in Boston's waterfront in generations."
The plan is still a draft. Public comment runs through September 18, 2026, and the final version doesn't go to Congress until 2028. Nothing here is asking you to price flood risk into an offer this month. What it does is confirm, with a federal dollar figure, that the exposure buyers have been implicitly pricing into older Waterfront buildings for years is real and large enough that the government is now treating it as a generational infrastructure problem rather than a maintenance line item.
For an individual building like Harbor Towers, that context matters two ways. First, its 2025 sea-wall project shows association-level defense spending is already happening independent of any city or federal timeline. Second, a public floodwall or storm surge barrier, if and when it's built, could reduce a specific building's future assessment risk, which is exactly the kind of detail worth asking about in board minutes rather than assuming from a listing photo.
What to Actually Check Before You Write an Offer
A lower price per square foot on the Waterfront isn't a discount if it's followed by a special assessment two years later. Before comparing a Waterfront unit against a Seaport one on price alone, ask for:
- The last three years of condo association meeting minutes, specifically any discussion of mechanical systems, roof condition, or planned resilience work
- Whether the building's reserve fund has a recent professional reserve study, not just a balance sheet number
- Whether the master policy is "bare walls" or "all-in." Massachusetts bare-walls policies cover only the exterior structure and common areas, leaving everything inside your unit's walls, flooring, cabinets, fixtures, to your own HO-6 policy
- Whether your HO-6 policy includes loss assessment coverage, which pays your share if the association levies a special assessment after a covered loss that exceeds the master policy's limits
- How the condo fee is calculated under the master deed. Massachusetts law lets associations base the formula on percentage interest, unit-to-whole square footage, or factors like location and limited common areas, so two units of the same size in the same building can carry different fees
Fannie Mae's 2026 project standards note that underfunded reserves are correlated with the kind of critical repairs that produce a special assessment, which is exactly the pattern Harbor Towers lived through in 2007. And because FEMA's Risk Rating 2.0 prices flood insurance at the property level, using elevation and distance to water rather than a flat neighborhood rate, two buildings a few blocks apart on the same waterfront can carry meaningfully different insurance costs. The number on a listing sheet won't tell you that. The building's own paperwork will.
Frequently Asked Questions
Does a lower HOA fee at an older Waterfront building mean lower total cost of ownership? Not necessarily. A lower fee can mean an association is deferring the same maintenance that a higher-fee building already budgets for. Ask when the fee was last increased and whether it has kept pace with reserve study recommendations, not just whether the number itself looks affordable.
Is Seaport actually safer from flooding than the Waterfront? Newer Seaport construction was built to more current flood-resilient codes, which is part of why insurance costs there tend to run lower, roughly $500 to $1,000 a year versus $600 to $1,500 in older, denser buildings elsewhere in the city. That's a code and construction-date difference, not a statement that either submarket is exempt from the coastal exposure the Army Corps plan addresses citywide.
How do I find out if a specific building has a pending or recent special assessment? Request the trustee meeting minutes for the past two to three years directly, or ask your agent to pull them as part of due diligence. This is standard practice in Massachusetts condo transactions and sellers are expected to provide it.
If you're weighing a Waterfront unit against a Seaport one, or trying to figure out what a specific building's fee and reserve history actually tell you, Rooney Real Estate has spent decades reading Boston condo documents for exactly this kind of detail. Contact Jackie for a consultation before you write an offer, not after.